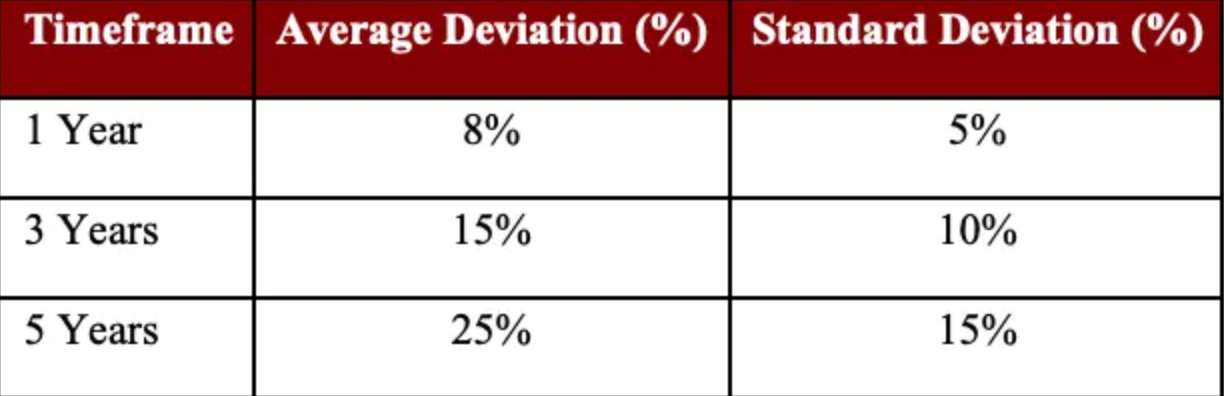
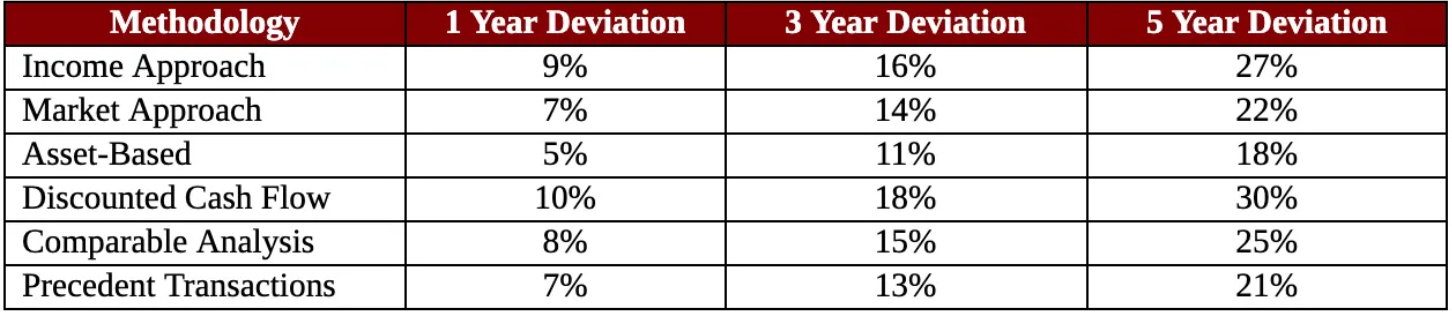
The stability of business valuation techniques varies widely depending on the approach each one estimates worth. Approaches based on assets typically show the least time-based fluctuation. They rely on consistent book values corrected for variables like depreciation and concentrate on concrete assets and liabilities that do not change much. Variations in one year are roughly 5% and increase to 18% over five years as a result of the stability of assets and liabilities.
Because the Income Approach calculates worth using anticipated future earnings, which can be influenced by operational, market, and economic uncertainties, it has a greater deviation. Over time, assumptions about expansion and costs can alter drastically. Variations for this technique span from 9% in one year to 27% over five years; longer projections introduce additional risk.
The method of Discounted Cash Flow (DCF) has the most volatility. Long-run hypotheses about cash flows and discounting rates determine it. Small changes in these assumptions can lead to large valuation changes. Deviations for DCF are 10% in one year and can reach 30% after five years, as economic conditions can undermine initial projections.
Moderate stability comes from market-based techniques including similar sales and past events. Market conditions affect these strategies; deviations over five years range from 7% to 22%. Likewise, Comparable Analysis varies depending on market trends; variations range from 8% to 25%.
Generally, the chosen valuation approach greatly impacts over time precision. To validate findings and adjust to shifting markets, analysts sometimes use a combination of approaches.
Factors Influencing Valuation Accuracy
Several internal and external factors impact valuation accuracy over time, making periodic reassessments essential. Below are key influencers that affect deviations:
Economic Conditions: Market downturns or booms can significantly impact valuation accuracy, as economic cycles influence cash flows, risk perception, and asset values.7
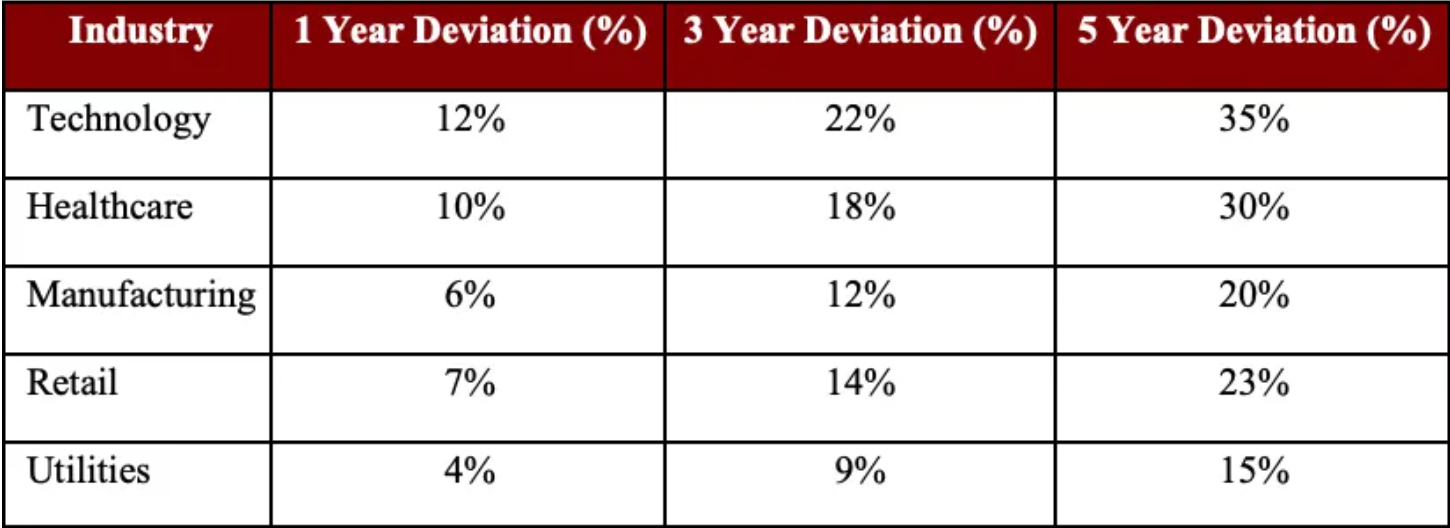
Industry Growth Rates: Rapidly evolving industries experience higher volatility in valuation projections, particularly in technology and healthcare sectors where disruption is common.
Regulatory Changes: Shifts in taxation, compliance requirements, or legal frameworks can affect financial outcomes and impact expected earnings, requiring updated valuations.8
Management Decisions: Internal strategic shifts, cost-cutting measures, or expansion plans can lead to variances between expected and actual valuation outcomes.9
Competitive Landscape: Increased competition or new market entrants can influence revenue projections and overall company value, requiring an assessment of original estimates.10
Inflation and Interest Rates: Changes in macroeconomic variables, such as inflation and interest rates, can influence discount rates used in valuation models, affecting future cash flow predictions.
Analysis of Overstatements vs. Understatements
A thorough analysis of valuation discrepancies uncovers a significant pattern: overstatements occur more frequently than understatements. This directional bias may stem from overly optimistic assumptions, the pressure to validate transaction prices, or forecasting models that inadequately consider risk factors. The inclination to inflate asset or income stream values heightens the risk of regulatory scrutiny, legal challenges, and financial errors.
Statistical evaluations reveal that around 62% of variations in business valuations lead to overstatements, where the projected value surpasses the actual outcome. In contrast, only 38% represent understatements. This disparity highlights the necessity of adopting retrospective testing, conservative forecasting methods, and hybrid valuation strategies to reduce upward bias.
Implications by Valuation Type
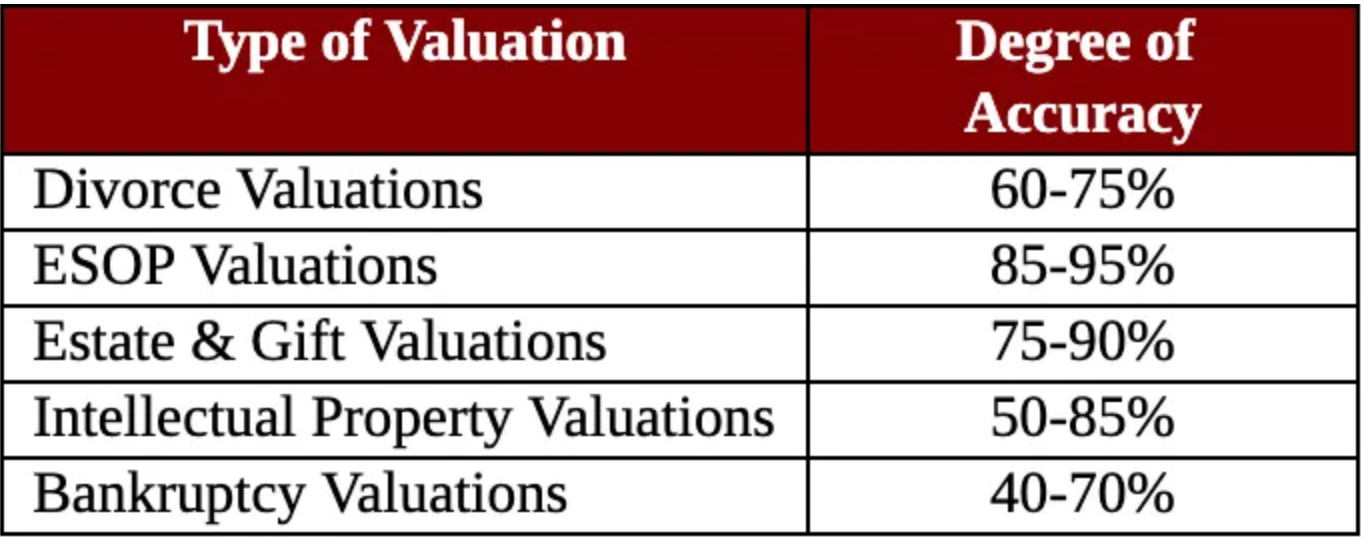
Valuation accuracy can vary greatly based on the context and the purpose of the valuation. For example, ESOP valuations, which are performed under strict scrutiny from the Department of Labor (DOL) and the IRS, generally achieve high accuracy, with reported ranges between 85% and 95%. This high level of precision is partly attributed to the regular updates and standardized methodologies that are mandated in ESOP engagements.11
On the other hand, valuations conducted for bankruptcy proceedings demonstrate much greater variability, with accuracy levels falling between 40% and 70%. The distressed conditions of these businesses, along with unpredictable cash flows and operational instability, lead to a broader range of deviation. Similarly, intellectual property valuations face comparable challenges due to their dependence on speculative forecasts regarding future commercialization and licensing opportunities.
Strategic Recommendations for Improved Accuracy
To enhance the dependability of business valuations, it is essential to establish several strategic practices as standard procedures. A fundamental recommendation is to implement retrospective valuation testing. By regularly comparing projected values with actual results, companies can uncover persistent biases or erroneous assumptions and modify their models as needed.
Moreover, employing a hybrid weighting model—such as distributing 40% to the Market Approach, 40% to the Income Approach, and 20% to the Asset-Based Approach—offers a comprehensive perspective that integrates various valuation methodologies. This probabilistic approach mitigates excessive reliance on any one method and protects against deviations caused by outliers.
Additionally, stochastic modeling techniques, such as Monte Carlo simulations, provide an extra layer of sophistication by simulating a spectrum of possible outcomes and assigning probabilities to each scenario. This is especially beneficial in industries characterized by volatility or rapid growth, where uncertainty is prevalent.
Furthermore, the integration of rolling valuation frameworks and cross-peer evaluations improves model adaptability and guarantees thorough internal validation.
Turning Accuracy into Strategic Value
Ultimately, achieving accurate valuations is not solely about adhering to technical standards; it also involves gaining strategic insights. Organizations that integrate validation processes and regularly revise their assumptions are better equipped for robust financial decision-making, enhanced regulatory confidence, and increased client trust. As the financial environment becomes increasingly intricate, the capacity to validate and justify valuation conclusions evolves from being merely a best practice to a significant competitive edge.
Valuation in High-Volatility Industries
Valuation results are extremely sensitive to the dynamics of the industry. In fields such as Technology and Healthcare, the inherent volatility increases the likelihood of substantial valuation discrepancies. These sectors undergo frequent regulatory changes, rapid cycles of innovation, and shifting consumer preferences, which can swiftly make forecasts outdated. Consequently, valuation techniques that depend heavily on future cash flow estimates, like Discounted Cash Flow (DCF), may be particularly susceptible in these contexts.12
In contrast, sectors like Utilities and Manufacturing display more stable revenue streams and slower rates of change. This consistency fosters more dependable valuation results, especially when employing methods based on historical performance and tangible assets. It is essential to acknowledge the impact of industry-specific factors when choosing valuation approaches and evaluating their long-term dependability.
Macroeconomic Influences on Valuation Accuracy
Broader macroeconomic factors significantly influence the precision of valuations. Changes in interest rates, inflation, and market liquidity can greatly impact discount rates and cost-of-capital assumptions, which are essential components of income-based and DCF valuation models. For instance, an unexpected increase in interest rates may lower present value estimates, resulting in valuations that are less than what was previously anticipated.13
During times of economic uncertainty, valuation analysts need to exercise extra caution when incorporating optimistic growth projections. Conducting stress tests and accounting for economic fluctuations can improve the robustness of models and offer stakeholders more realistic expectations regarding potential valuation ranges.
Role of Professional Judgment and Bias Mitigation
Although valuation methods are based on financial principles, the importance of professional judgment is significant. Analysts need to use their discretion when choosing comparable companies, setting discount rates, or predicting future earnings. This element of subjectivity brings the potential for cognitive biases—such as optimism bias, confirmation bias, and anchoring—that can skew valuation results.14
To mitigate these risks, companies should establish structured review processes, promote differing opinions during model creation, and perform sensitivity analyses to assess the effects of changing assumptions. Additionally, maintaining transparency in documenting key inputs and the reasoning behind selections enhances both defensibility and trust.
Value of Cross-Validation and Peer Review
Implementing cross-validation protocols and peer evaluations provides a robust method for improving the reliability of valuations. Independent assessments can reveal concealed assumptions, incorrect applications of methodology, or oversights in the analysis of financial information. Particularly in critical situations—like litigation, mergers and acquisitions, or regulatory disclosures—gaining insights from various experts diminishes the chances of mistakes and enhances the trustworthiness of the valuation report.
Conclusion
Business valuations are not just one-time estimates; they are ongoing evaluations with important strategic, legal, and financial effects. Valuations tend to lose accuracy over time, particularly in uncertain sectors. Therefore, valuators must use more careful assumptions and strict testing methods to provide reliable estimates.
To improve the accuracy of valuations, professionals should utilize retrospective testing, hybrid models, and advanced techniques like Monte Carlo analysis. Regular peer reviews, constant updates, and a deep understanding of industry and economic trends are crucial for ensuring valuations are accurate.
In summary, using these practices enhances credibility, boosts stakeholder confidence, reduces regulatory risks, and makes valuations more strategic. Valuations are generally most accurate within the first year and become less reliable in volatile industries. The Asset-Based Approach offers stable estimates, while Income-Based models can vary more due to reliance on forecasts.
For business owners, investors, and analysts, regular reassessments are essential. Adapting to economic changes and using various methodologies can improve long-term accuracy. Frequent valuation reviews help ensure informed financial decisions based on current market conditions.